Property damage is stressful enough without having to decode insurance paperwork at the same time. After a fire, flood, storm, or other unexpected event, homeowners may need to document losses, understand coverage, meet filing requirements, and coordinate repairs while trying to get life back to normal.
Insurance claim assistance for property damage restoration can help make that process more organized. Restoration professionals can provide damage documentation, photographs, repair estimates, and other information insurers may request while keeping restoration work aligned with the claims process.
Homeowners still work directly with their insurance carrier or adjuster on coverage and settlement decisions. Understanding how restoration and insurance claims fit together can help you avoid preventable delays, maintain clearer records, and move from initial damage assessment toward repairs with fewer complications.
How Insurance Claim Assistance Simplifies the Restoration Process
Understanding the Property Damage Insurance Claim Process
Property damage can leave homeowners dealing with two complicated processes at once: restoring the property and navigating an insurance claim. Understanding how those processes overlap can make it easier to document the loss, communicate with the insurer, and keep restoration work moving.
Insurance claim assistance from an experienced restoration contractor can also help organize the repair side of the claim. Restor-It states that it works with insurance companies during restoration projects and provides assistance with the claims process.
Document the Damage Before Cleanup and Repairs Begin
Once the property is safe to enter, create a detailed record of the damage before removing materials or making permanent repairs. Take wide-angle photographs showing entire rooms as well as close-up images of damaged flooring, walls, ceilings, cabinets, furniture, and personal belongings. Video can provide additional context about the extent of the loss.
Write down when the incident occurred, what you believe caused it, which areas were affected, and any immediate actions taken to protect the property. Restor-It’s guidance on emergency water damage restoration similarly recommends documenting visible damage and affected belongings for an insurance claim.
Avoid throwing damaged materials or belongings away before documenting them unless they pose an immediate safety concern or your insurer or restoration professional advises otherwise.
Notify Your Insurance Company and Review Your Coverage
Report the loss to your insurance provider promptly and ask what documentation it requires. Your insurer can explain the next steps, including whether an adjuster will inspect the property and how estimates or invoices should be submitted.
This is also the time to review the applicable parts of your policy. Coverage limits, deductibles, exclusions, and the cause of the loss can all influence how a claim is handled. Do not assume that every type of property damage is covered in the same way.
For example, storm losses can involve different coverage questions depending on whether the damage resulted from wind, water intrusion, or flooding. Restor-It’s guide to storm damage and insurance considerations for Atlanta homeowners discusses documentation, adjuster inspections, deductibles, exclusions, and the importance of understanding policy terms.
Begin Mitigation Without Losing Track of Claim Documentation
Waiting for the entire claim to be resolved before addressing active damage can allow conditions to worsen. A leaking pipe, standing water, exposed opening, or wet building materials may require immediate attention.
Restoration professionals can assess affected areas, identify moisture or structural concerns, document the work required, and begin appropriate mitigation. Restor-It notes that its emergency remediation process may include an initial assessment, restoration planning, execution, insurance coordination, and a final inspection.
Keep records of emergency work, estimates, invoices, receipts, photographs, and communication associated with the loss. The goal is to create a clear timeline showing the original damage and the steps taken afterward.
Understand the Restoration Estimate and Adjuster’s Assessment
An insurance adjuster may inspect the property and evaluate the scope of covered damage. Meanwhile, the restoration contractor evaluates what is required to mitigate damage and repair the property.
These assessments serve different purposes, so questions can arise about the scope of work, materials, or repair requirements. Ask for clarification when something in an estimate or claim document does not make sense rather than assuming that every document will match automatically.
The process can become especially detailed after a major loss. Restor-It’s guide to fire damage recovery and insurance claims explains why photographs, videos, inventories, policy review, and communication with the insurance provider become important parts of recovery after a fire.
Keep the Claim Organized From Start to Finish
Good organization is one of the most useful forms of insurance claim assistance. Create a dedicated folder for the claim number, policy information, adjuster contact details, photographs, estimates, invoices, receipts, emails, and notes from phone conversations.
Keep a simple timeline as well. Record when the loss occurred, when it was reported, when inspections took place, when mitigation began, and when important documents were submitted.
Most importantly, separate questions about insurance coverage from questions about restoration work. Your insurer determines coverage under the policy, while restoration professionals can document damage, explain the necessary restoration scope, provide estimates, and coordinate relevant project information.
That distinction helps homeowners understand who to contact when questions arise and makes the property damage claim process easier to manage from the initial loss through completed repairs.
How to Document Property Damage for an Insurance Claim
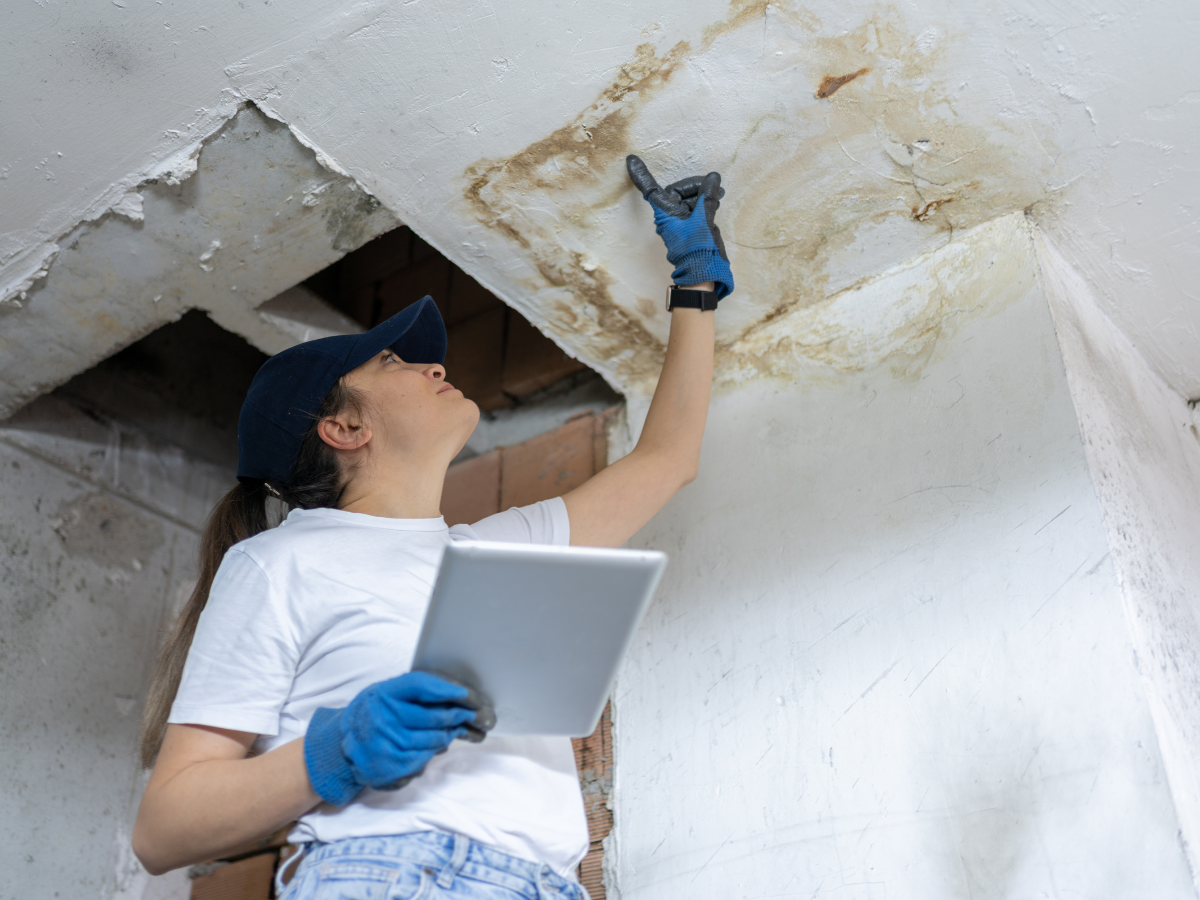
Strong documentation creates a clear record of what happened, what was damaged, and what work was required afterward. It cannot guarantee that an insurer will approve a claim or cover every expense, but it can make conversations with adjusters, restoration contractors, and other parties much easier to follow.
This section should also stay focused on documentation rather than repeating the full claims process covered earlier. The goal here is practical: build a claim file that someone unfamiliar with the loss can review and understand.
Photograph the Damage From Multiple Perspectives
Begin documenting the property as soon as it is safe to do so and, when practical, before cleanup changes the scene.
Take wide-angle photographs that establish where the damage occurred, then move closer to capture individual problems. For example, a water loss might require images of the entire affected room as well as close-ups of damaged flooring, drywall, cabinetry, or belongings.
Video can provide additional context, particularly when damage extends across several rooms or is difficult to represent in individual photographs.
Restor-It recommends documenting visible water damage and affected belongings as part of the insurance process in its guide to emergency water damage restoration.
Do not put yourself at risk to get better evidence. Fire-damaged structures, contaminated water, electrical hazards, unstable building materials, and other dangerous conditions should be assessed safely.
Create a Room-by-Room Inventory of Damaged Property
A single list labeled “damaged furniture” will not provide much detail several weeks into a claim.
Instead, organize affected belongings by room and record enough information to identify each item. Depending on the loss, useful details may include the item description, approximate age, condition before the incident, visible damage, and any receipts or purchase records you still have.
Avoid guessing at replacement values simply to fill every field immediately. Gather supporting records where available and ask your insurer how it wants personal-property values documented.
Fire losses can make inventories particularly important because both structural materials and belongings may be affected. Restor-It’s fire damage recovery guide recommends photographs, videos, written records of affected property, and organized communication with the insurer.
Keep Restoration Estimates, Reports, and Invoices Together
Insurance claim assistance often becomes easier when the documentation from the restoration work is organized alongside the homeowner’s own records.
Save written estimates, scopes of work, invoices, inspection findings, moisture documentation when provided, and records of emergency services. These materials help establish what professionals found and what restoration work was recommended or completed.
Restor-It states that it works with insurance companies and provides documentation and communication during restoration projects. Its emergency restoration services include water mitigation, reconstruction, fire and smoke restoration, mold remediation, and other disaster recovery work.
Professional estimates do not determine what an insurance policy covers. They document the restoration scope and associated work, while the insurer evaluates coverage according to the policy.
Save Receipts for Emergency and Temporary Expenses
Property damage can generate expenses before permanent repairs even begin. You may need tarps, temporary protective materials, emergency services, cleanup supplies, or other measures intended to prevent additional damage.
Keep those receipts rather than trying to reconstruct the expenses later.
After storm damage, for example, Restor-It recommends saving receipts associated with emergency repairs and temporary protective measures and providing relevant documentation during discussions with the adjuster. Its Atlanta storm recovery guide also recommends documenting both exterior and interior damage before major cleanup or repairs begin.
Build One Claim File and Maintain a Timeline
A simple folder structure can prevent insurance documents from becoming scattered across emails, phones, and paper files.
Consider keeping separate folders for:
- Damage photos and videos
- Damaged-property inventory
- Policy and claim information
- Restoration estimates and invoices
- Receipts
- Insurance correspondence
Add a basic timeline recording the date of loss, when the insurer was notified, inspections, restoration visits, estimates received, documents submitted, and important conversations.
For phone calls, note the date, person you spoke with, and the main points discussed. Save important email correspondence rather than relying on memory.
Update the Documentation as Restoration Progresses
The claim file should not stop with photographs taken on day one.
Take additional photos when damaged materials are exposed, when the scope becomes clearer, and when significant restoration stages are completed. Keep updated estimates or change documentation if previously hidden damage alters the work required.
For mold-related losses, Restor-It similarly advises retaining photographs, detailed damage records, professional assessments, and correspondence with remediation providers. Its mold remediation information provides another useful resource for situations where moisture damage develops into a remediation issue.
Good property documentation does not need to be elaborate. It needs to be consistent, specific, and easy to retrieve. That creates a stronger factual record for insurance discussions and gives homeowners, adjusters, and restoration professionals a clearer picture of how the loss and recovery progressed.
How Restoration Insurance Billing and Contractor Invoices Work
Restoration billing can become one of the more confusing parts of a property damage claim because several documents may be moving between the homeowner, restoration contractor, and insurance company at the same time.
An estimate may describe the anticipated scope of work, while invoices document services actually performed. The insurer then evaluates those costs according to the terms of the policy and its own claim review.
Insurance claim assistance from a restoration contractor can help organize this process, but it is important to understand the boundaries. Restor-It states that it works with insurance companies and provides documentation and communication during restoration projects.
The company can support the restoration side of the claim, while the insurance carrier remains responsible for determining coverage and payment under the policy.
Understand the Difference Between Estimates and Final Invoices
A restoration estimate is typically prepared before or during the early stages of work and describes what the contractor expects will be necessary based on the visible damage and initial assessment.
An invoice reflects work that has actually been performed or materials that have been provided. If additional damage becomes visible after demolition or drying begins, the final scope may differ from the first estimate.
That difference does not automatically mean something is wrong. Property damage can conceal moisture, damaged subflooring, compromised drywall, or other conditions that are difficult to evaluate until affected materials are opened or removed.
Homeowners should keep the original estimate, revised scopes, change documentation, and final invoices together so they can see how the project developed.
What Should a Restoration Invoice Include?
A useful contractor invoice should make it reasonably clear what the homeowner is being charged for rather than presenting only one unexplained total.
Depending on the project, the documentation may include:
- Labor associated with mitigation, cleanup, reconstruction, or repair
- Materials used during the project
- Equipment or specialized restoration services
- Individual areas or tasks included in the scope
- Applicable taxes or additional charges
- Payments already received and remaining balances
The level of detail can vary according to the contractor and project. If an item is unclear, ask the contractor to explain what it represents before assuming it should or should not be covered.
Restor-It’s emergency restoration services cover several types of disaster recovery work, including water damage mitigation, reconstruction and repairs, fire and smoke restoration, and mold remediation. Different losses can therefore produce very different scopes and billing documentation.
How Contractor Billing Connects With the Insurance Claim
A restoration contractor may communicate project information to the insurance company or provide documentation that supports the claim. Restor-It specifically states that it collaborates with insurance companies to streamline the claims process and provide proper documentation and communication.
That does not mean every amount appearing on an invoice is automatically payable by the insurer.
Coverage may depend on the cause of damage, policy exclusions, deductibles, limits, depreciation provisions, and other policy terms. There may also be differences between what the contractor recommends restoring and what the insurer initially recognizes within the covered scope.
If those differences arise, ask for explanations from the appropriate party rather than assuming the contractor and insurer are making the same decision. The contractor can explain the restoration work and associated charges. The insurer can explain coverage decisions under the policy.
Keep Track of Payments and Remaining Balances
Homeowners should maintain their own record of what has been billed, what the insurance company has issued, and what has already been paid to the restoration company.
Restor-It’s website provides options for invoice payment by ACH or card, which reinforces the importance of treating contractor billing as its own financial record rather than assuming that all transactions occur directly between the restoration company and insurer.
Keep copies of:
- Contractor estimates and invoices
- Insurance payment or settlement documents
- Deductible information
- Receipts for payments you make
- Revised scopes or supplements
- Emails discussing billing questions
- Records of temporary or emergency expenses
This makes it easier to identify what a payment relates to and whether an outstanding balance still exists.
Ask About Billing Before Restoration Work Expands
Insurance claim assistance is most useful when billing expectations are discussed early rather than after repairs are complete.
Before substantial restoration work begins, ask how estimates will be prepared, how changes to the scope will be documented, whether invoices are submitted to the insurance company, and who is ultimately responsible for paying the contractor.
For larger losses that require rebuilding after mitigation, Restor-It’s home renovation and restoration services can also become relevant as the project transitions from damage removal into reconstruction. The company’s site notes that it provides insurance claim assistance as part of its disaster recovery support.
The most important principle is to keep billing, restoration scope, and insurance coverage related but separate. A contractor invoice documents the work and charges associated with restoring the property.
The insurance company evaluates what the policy will pay. Keeping those roles clear, maintaining detailed records, and asking questions as the scope changes can make restoration billing far easier to understand throughout the claim.
What to Do When a Property Damage Insurance Claim Is Denied
An insurance claim denial does not necessarily end the claims process. It means the insurer has determined that some or all of the reported loss is not payable based on its current assessment and interpretation of the policy.
The next step is to understand exactly why that decision was made before deciding whether there is a reasonable basis to challenge it.
For homeowners already dealing with repairs, the distinction matters. Insurance claim assistance from a restoration contractor can help with damage documentation, estimates, restoration records, and other information related to the physical loss.
However, contractors do not determine insurance coverage or make legal decisions about whether an insurer must pay a claim.
Start With the Insurer’s Written Explanation
Read the denial letter carefully rather than focusing only on the final decision. The insurer should identify why the claim, or a particular portion of it, was denied. Compare that explanation with your policy documents and the evidence you submitted.
Common issues may involve:
- A cause of loss the insurer considers excluded from the policy
- Questions about whether damage resulted from a sudden event or a longer-term condition
- Insufficient evidence showing the cause or extent of the damage
- Disagreement about which repairs are necessary
- Missed notification, documentation, or filing requirements
- Policy limits, deductibles, or other coverage provisions
The reason matters because the appropriate response to missing documentation is very different from the response to a dispute over policy language.
For example, homeowners dealing with water-related losses can review Restor-It’s guidance on documenting damage for an insurance claim after water damage. Photographs, videos, written descriptions, and records of the event can help establish what happened and what areas of the property were affected.
Determine Whether Additional Evidence Could Address the Dispute
If the insurer’s decision involves the extent of damage or proposed restoration work, review what evidence was included with the original claim.
A restoration professional may be able to provide photographs, moisture readings, inspection findings, estimates, invoices, or an explanation of the work performed.
Restor-It’s emergency remediation guidance also emphasizes documenting damage and maintaining supporting information throughout the restoration and claims process.
This is where insurance claim assistance can be particularly useful. A contractor who inspected the property can explain the physical damage and why specific restoration work was recommended. That documentation may help clarify differences between the contractor’s scope and the insurer’s initial assessment.
Avoid adding information simply to make the claim appear stronger. Documentation should accurately reflect the condition of the property and the work that was actually necessary.
How to Request Reconsideration or Appeal a Denied Claim
If you believe the denial resulted from incomplete information, an incorrect damage assessment, or another issue that can be addressed, check your insurer’s instructions for disputing the decision.
A practical response usually begins with three steps:
- Identify the disputed issue. Refer to the specific reason given by the insurer rather than submitting the same claim again without explanation.
- Gather relevant evidence. Include only documentation that helps address that issue, such as photographs, contractor estimates, inspection reports, receipts, or updated assessments.
- Keep the communication documented. Save copies of letters, emails, submitted files, and notes about conversations with adjusters.
After fire damage, documentation can become especially extensive because structural damage, smoke, soot, water from firefighting efforts, and damaged belongings may all need to be evaluated. Restor-It’s guide to fire damage recovery and insurance claims discusses keeping detailed records and reviewing policy provisions during that process.
Know When the Disagreement Goes Beyond Restoration Documentation
Not every insurance dispute can be resolved by supplying another estimate or additional photographs.
A disagreement may center on the interpretation of an exclusion, the cause of the loss, valuation, or another coverage issue. At that point, the homeowner may need assistance beyond what a restoration contractor can appropriately provide.
Depending on the circumstances and local regulations, that could involve discussing the claim with the insurance agent, requesting further review from the carrier, consulting a licensed public adjuster, filing a complaint with the appropriate insurance regulator, or seeking advice from an attorney experienced in insurance matters.
The appropriate route depends on the nature of the dispute and the procedures available under the policy and applicable law.
Build a Stronger Record Before a Dispute Develops
The best time to prepare for a possible disagreement is before one occurs. Keep photographs of the original damage, estimates, invoices, receipts, communications, and records showing how the restoration scope changed over time.
Storm losses are a good example. Restor-It’s guide to documenting storm damage for insurance claims recommends recording both interior and exterior damage, keeping written details about the event, and retaining receipts for emergency protective measures.
Clear records cannot guarantee that an insurer will approve a claim, but they make it easier to establish what happened, what was damaged, and what restoration work was required. If questions or disputes arise, that evidence also gives homeowners, restoration professionals, adjusters, and other appropriate advisers a much clearer factual record to work from.
How Insurance Adjusters and Restoration Contractors Work Together
A property damage claim often requires two processes to move forward at the same time. The insurance company needs enough information to evaluate the loss and determine coverage, while the restoration contractor needs to assess the property, prevent additional damage, and establish what work is required.
Understanding where those responsibilities overlap, and where they do not, can prevent confusion. Insurance claim assistance from a restoration company primarily supports the technical side of the claim through assessments, estimates, photographs, work records, and communication about the restoration scope.
The insurance adjuster evaluates that information according to the homeowner’s policy.
What Is the Insurance Adjuster’s Role in a Property Damage Claim?
An insurance adjuster investigates the reported loss on behalf of the insurance company. This may involve inspecting the property, reviewing photographs and other evidence, examining contractor estimates, asking questions about how the damage occurred, and determining which portions of the loss fall within the policy’s coverage.
During an inspection, homeowners should be prepared to provide relevant records rather than relying on the adjuster to identify every affected area independently. Restor-It’s guidance on preparing for storm damage inspections and insurance adjusters recommends having photographs, receipts, contractor estimates, and other documentation available when discussing the loss.
The adjuster’s estimate and the contractor’s estimate may not always match. That does not automatically indicate a problem. The two professionals approach the property from different perspectives. The adjuster is evaluating the claim for the insurer, while the contractor is determining what work is necessary to restore the damaged property.
What Does the Restoration Contractor Contribute?
A restoration contractor provides information grounded in the physical condition of the property. Depending on the loss, this can involve identifying affected materials, checking for hidden moisture, evaluating the extent of smoke or fire damage, developing a restoration plan, and preparing an estimate for the required work.
A detailed scope is especially valuable because property damage is not always fully visible during an initial walkthrough. Demolition or further inspection may uncover additional deterioration that changes what needs to be repaired.
Restor-It’s article on how the mold remediation process is assessed and priced offers a useful example. It explains how an estimate can connect individual costs with specific work such as containment, filtration, removal of affected materials, and drying. That level of detail gives the homeowner and other parties a clearer basis for understanding why particular work has been recommended.
How Should Homeowners Handle Differences Between Estimates?
A difference between an adjuster’s assessment and a contractor’s proposed scope should be investigated rather than treated immediately as a dispute.
Start by comparing the documents line by line. Look for differences in affected areas, quantities, materials, labor, demolition, drying, repairs, or work that one estimate includes and the other does not.
If the contractor has included additional work, ask why it is necessary and what evidence supports it. If the insurer has omitted or reduced an item, ask the adjuster for an explanation. Photographs, inspection findings, measurements, invoices, and written scope changes can help establish what actually occurred at the property.
This is also why choosing a contractor who communicates clearly matters. Restor-It’s guidance on evaluating a contractor’s scope, estimates, and communication practices recommends reviewing detailed contracts and line-item estimates while establishing how project updates and changes will be communicated.
Keep Communication Organized Without Blurring Responsibilities
The homeowner remains an important link between the insurer and restoration company, even when the contractor communicates directly with the adjuster.
Keep copies of estimates, inspection reports, photographs, invoices, approvals, change orders, and important correspondence. When something changes, document what changed, why it changed, and who was notified.
Insurance claim assistance can make the restoration side easier to coordinate, but a contractor should not be treated as the person making coverage decisions. Likewise, an insurance adjuster’s approval of a claim does not replace the contractor’s responsibility to explain the proposed restoration work.
Why Clear Roles Matter During Restoration
The strongest working relationship is not one in which the contractor and adjuster perform the same job. It is one in which each provides the information necessary for the homeowner to understand both sides of the process.
The adjuster addresses the insurance claim and applicable policy coverage. The restoration contractor addresses the condition of the property, necessary work, project scope, and associated costs. The homeowner keeps records, asks questions, and makes sure important information reaches the appropriate party.
That separation becomes particularly important when restoration moves beyond immediate cleanup and into repairs. Restor-It’s guidance on professional drywall repair and contractor estimates, for example, recommends obtaining a written estimate that explains the scope, materials, labor costs, and expected timeline.
Clear documentation and defined responsibilities make it easier to identify whether a question concerns the restoration work, the contractor’s estimate, or the insurance company’s coverage decision.
That can reduce unnecessary back-and-forth and help homeowners stay better informed as both the claim and property recovery progress.
Restoration Insurance Claim Costs, Trends, and Changing Requirements
Property damage claims are affected by more than the visible damage itself. The cost of labor and materials, the condition of the property, the complexity of repairs, and changes discovered after work begins can all influence the final restoration bill.
Insurance policies and claim requirements add another layer, since the amount an insurer covers depends on the specific terms of the policy.
For homeowners seeking insurance claim assistance, understanding these moving parts makes it easier to review estimates, recognize why a restoration scope may change, and keep the documentation needed as a claim progresses.
What Causes Restoration Costs to Change?
Restoration pricing is highly dependent on the actual scope of work. Two properties affected by the same type of incident can require substantially different repairs depending on the materials involved, how far the damage spread, and whether problems exist beneath finished surfaces.
Labor and material selection also matter. Restor-It’s discussion of drywall and plaster costs provides a useful example. Drywall generally requires less labor than plaster, while specialty finishes, historic restoration work, and more complex installations can increase costs.
Flooring creates similar variables. Damage that initially appears limited to the finished floor may reveal problems with the subfloor once materials are removed. Restor-It’s carpet replacement guide explains how removal, disposal, padding, installation labor, and necessary subfloor repairs can all contribute to the total project cost.
These details matter during an insurance claim because a broad estimate may not tell the entire story. Homeowners should look at what work is included, which materials are being replaced, and whether preparation, demolition, disposal, or related repairs are accounted for.
Why Restoration Estimates May Change After Work Begins
An initial inspection provides a starting point, but not every condition is visible before demolition or material removal. Moisture beneath flooring, damaged drywall, deteriorated subfloors, or other concealed problems may become apparent only after restoration is underway.
That does not mean every increase in cost is automatically justified. Changes should be documented clearly. A revised estimate or change order should identify what was discovered, what additional work is recommended, and how the discovery affects the original scope.
Restor-It’s guidance on professional drywall repair reinforces the value of written estimates that identify the scope, materials, labor costs, and expected timeline.
Clear documentation becomes particularly important when the scope changes because it creates a record that homeowners can compare with earlier estimates and discuss with their insurer.
Homeowners should retain both the original and revised versions rather than replacing one with the other. Photographs of newly discovered damage, contractor notes, invoices, and written communications can help establish why additional work became necessary.
How Material and Labor Costs Affect an Insurance Claim
A restoration estimate reflects current repair conditions, not necessarily what similar work cost several years ago. Material selection, skilled labor, site preparation, disposal, permits, and the complexity of the project can all affect pricing.
Restor-It’s broader Atlanta home renovation cost guide illustrates how scope, materials, labor, existing property conditions, permits, and specialized work can influence a project’s budget. It also recommends line-item estimates that separate expenses such as labor, materials, permits, and disposal.
For an insurance claim, that level of detail can be more useful than a single total. It allows the homeowner and insurer to see what the contractor is proposing and where costs originate.
It is also important to separate the contractor’s estimate from the insurer’s coverage decision. A restoration contractor can document the work required and its expected cost, but the insurance company determines what is covered under the policy.
Deductibles, exclusions, coverage limits, depreciation, and other policy provisions may affect the homeowner’s final reimbursement.
Staying Informed Without Relying on Outdated Claim Advice
Insurance requirements and restoration costs can change, so homeowners should be careful with generalized advice found online. The policy itself should remain the primary reference for questions about coverage, deadlines, exclusions, and claim obligations.
For restoration-related information, homeowners can also review recent projects and educational resources to better understand the types of work that may follow property damage.
Restor-It’s restoration and flooring project gallery provides examples of completed property work, while its broader resource library covers restoration, repairs, flooring, and renovation topics.
Insurance claim assistance is most useful when it helps keep the restoration side of the claim well documented. Maintain estimates, invoices, photographs, work authorizations, correspondence, and records of scope changes in one place. If costs or required repairs change, ask for the reason in writing.
That creates a clearer record for everyone involved and helps distinguish three separate questions: what damage occurred, what work is required to restore the property, and what portion of that work is covered by the insurance policy.
Conclusion
Navigating an insurance claim after property damage can feel overwhelming, especially when you’re also dealing with repairs, documentation, and the disruption to your home or business.
Understanding the claims process, keeping accurate records, and working with experienced restoration professionals can help make recovery more manageable and ensure necessary repairs are properly documented.
Whether you’re dealing with water, fire, storm, or other property damage, having a knowledgeable restoration team on your side can help you move forward with confidence.
For dependable property damage restoration and insurance claim assistance, choose Restor-It., Inc. If you’re ready to restore your property and simplify the recovery process, call (678) 355-6645 to speak with the team at Restor-It, Inc. or request your free quote today.